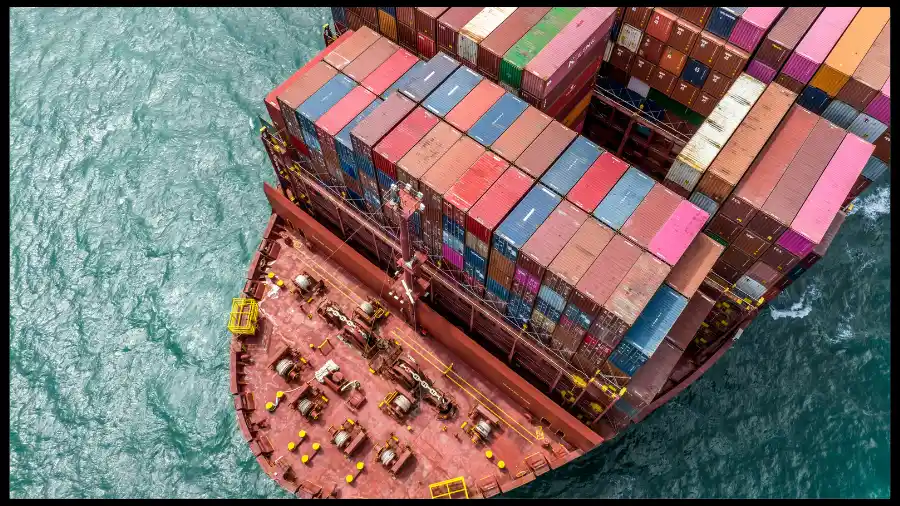
Containership contracting in 2025 has surged to a fresh all time high, with around 633 ships totaling about 5.08m teu ordered so far, overtaking the previous peaks set in 2021 and 2024. Chinese shipyards have captured close to three quarters of the new capacity, while the orderbook now equals roughly one third of the existing fleet. For owners and charterers, that means a larger wave of new, fuel efficient tonnage heading for delivery into a market that may already see supply outpace demand over the next few years.
Click here for 30 second summary
Record 2025 boxship orders and the next capacity wave
Orders for around 633 containerships, about 5.08 million teu in total, make 2025 a new record year for boxship contracting. The orderbook now sits at roughly one third of the existing fleet, with a heavy delivery run expected late this decade. How hard this bites will depend on trade growth, routing choices and how much older tonnage leaves the water.
Scale and timing of new capacity
The contracting surge locks in a steady stream of deliveries through roughly 2027 to 2030, with Chinese yards holding the bulk of the work. Even with some delays and cancellations, net fleet growth is likely to stay ahead of historic trade growth unless capacity is absorbed by slow steaming or structural congestion.
Impact on freight, fleet mix and CII
As diversions ease and services move back to shorter routes, the same ship pool can move more cargo. That increases the risk of softer mid cycle freight rates, especially for older ships with weaker efficiency and CII scores, while modern and dual fuel designs are better placed to win long term contracts and time charter cover.
Asset values and yard dynamics
A crowded orderbook supports newbuild prices and limits late buyers to fewer, more expensive slots. Secondhand values are likely to diverge further, with young eco vessels and prompt resales holding up better than midlife and older units that will have to compete head on with incoming ships on key trades.
Bottom line
The record 2025 ordering year turns containership supply into a central theme for the next cycle. For boxship owners and charterers it means that decisions on speed, scrapping and contract mix will sit alongside demand trends in determining whether this delivery wave feels manageable or heavy once the ships arrive.
Record Containership Orders In 2025
Item
Summary
Business Mechanics
Bottom-Line Effect
Order volume in 2025
Around 633 containerships totaling about 5.08m teu have been ordered in 2025, overtaking earlier record years and lifting the container orderbook to one of its largest levels on record.
The new contracting wave reflects a mix of fleet renewal, energy transition planning and opportunistic ordering while Asian yard slots are still available at attractive terms compared with likely future prices.
📈 Strong pipeline of new capacity for 2027 to 2030; 📉 higher risk of oversupply if demand growth underperforms expectations.
Orderbook to fleet ratio
The container orderbook is now roughly one third of the existing fleet, with analysts warning that scheduled deliveries could outpace expected demand for several years.
A high ratio means that even moderate slippage or scrapping will still leave net fleet growth well above trend trade growth, unless extended slow steaming or new regulations soak up capacity.
📉 Downward pressure on mid cycle freight rate assumptions; 📈 more focus on cost base and vessel efficiency to stay competitive.
Chinese yard dominance
Around 72 percent of the teu ordered this year has gone to Chinese shipyards, which are taking the lead in both large and feeder boxship construction.
Concentration of orders in China reflects available slots, competitive pricing and support for alternative fuel designs, but also increases dependence on a limited group of builders for deliveries.
📈 Stronger negotiating leverage for leading Chinese yards; 📉 less pricing power for buyers that still need nearby slots.
Feeder and mid size renewal
Brokers highlight a sustained push for new feeder and mid size ships, tightening available berths for these segments in the second half of the decade.
Many regional trades rely on older feeder tonnage with weak efficiency scores. Replacing those units with modern designs reshapes cost per teu, emissions profiles and charter market dynamics on hub and spoke networks.
📈 Better fuel and maintenance economics for operators with new vessels; 📉 greater retirement pressure on older feeders with weaker CII ratings.
Fuel and emissions profile
A growing slice of new orders are prepared for alternative fuels or advanced efficiency packages, while much of the in water fleet still runs on older designs.
Increasing regulatory pressure and customer expectations push carriers to line up more efficient ships that can secure better emissions ratings and long term contracts from cargo owners with climate targets.
📈 Premium charter and cargo opportunities for efficient and dual fuel newbuilds; 📉 discount or shorter employment for high emitting legacy ships.
Demand and routing outlook
Analysts warn that if services return to normal Suez and Red Sea routings and slow steaming reverses, effective demand for tonnage could ease just as new ships are delivered.
Temporary congestion, diversions and slow steaming increase tonne day requirements, masking underlying oversupply. If those effects fade, the same fleet will cover more trade with fewer ship days.
📉 Risk of weaker earnings once disruption premiums fade; 📈 incentive to keep slower speeds or adjust network design to stabilise capacity use.
Yard pricing and slots
Heavy container contracting tightens large yard schedules in China and elsewhere, with some reports of limited slots and firming prices for late decade deliveries.
With orderbooks filling, builders can be more selective on terms, payment structures and technical specifications, particularly for complex or dual fuel designs.
📈 Earlier movers lock in more favorable delivery windows; 📉 latecomers may face higher newbuild prices or need to look at resale tonnage.
Asset values and S&P
A swollen pipeline of competitive new ships influences secondhand pricing and scrap timing, especially for midlife and older vessels that will compete directly with incoming eco designs.
Buyers and financiers must price in not only near term earnings but also the future rate environment once most of the 2025 contracting wave hits the water, which can widen the value gap between older and modern ships.
📈 Support for younger eco ships and prompt resales; 📉 softer residual values and earlier recycling for less efficient units.
Notes: Order data and yard shares reflect public market commentary and container market updates as of mid December 2025. Effects will vary by size segment, trade lane exposure and individual fleet age and efficiency mix.
Next 12 to 24 months
Market still trades on geopolitics, routing choice and slow steaming. Orderbook noise is there but feels distant while disruption keeps tonne days high.
Delivery wave 2027 to 2030
Record contracting turns into steady monthly deliveries. Effective supply is likely to rise even if some slippage and scrapping take heat out of the numbers.
Longer view
Fleet age and efficiency gaps widen. Large owners with renewal already booked sit differently to operators that rely on older ships or short notice charters.
Trade scenario
Capacity picture
Freight and asset signal
Stronger trade growth
Resilient consumer and manufacturing demand absorb a large share of the delivery wave, with congestion pockets and optional slow steaming still in play.
📈 Support for time charter cover and values on modern ships, even with a big orderbook. Older units feel more cyclical but still find work in busy years.
Base case demand
Trade continues to grow, but at a slower pace than ordered capacity. Effective supply is pulled higher once diversions ease and services normalise.
Weaker trade and fewer diversions reveal a clear surplus. Some services are cut, and the scrapping queue grows for less efficient tonnage.
📉 Sharper pressure on freight and charter rates, particularly on older ships. 📈 Gap widens between eco ships with long cover and exposed spot tonnage.
Where order pressure feels strongest
Asia to Europe mainline
high
Transpacific major lanes
elevated
Regional and feeder trades
building
Bars are qualitative and reflect where a record orderbook is most likely to weigh on future capacity and pricing conversations.
Record breaking boxship contracting in 2025 locks in a heavy delivery run for the second half of the decade, particularly on Asia to Europe and other mainline trades. How painful that becomes for earnings will depend on the balance between trade growth, routing choices and scrapping, but the direction of travel is clear: modern, efficient ships are positioned to defend utilisation and value, while older units face a tougher fight for work once the current disruption premium fades.