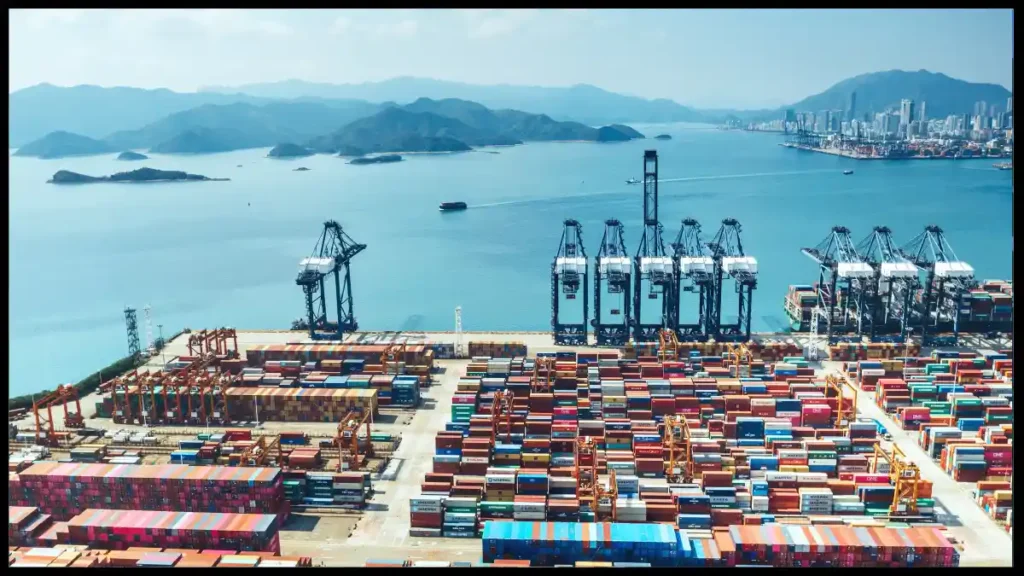
China began collecting special port fees on U.S.-linked vessels on October 14, 2025, starting at 400 yuan per net ton and stepping up to 1,120 yuan by 2028. Early application included a roughly 12.1 million yuan charge, about $1.7 million, for the Matson Waikiki at Shanghai. Chinese-built ships are exempt, and authorities outlined limits such as payment at the first Chinese port only and a cap on how many voyages are charged each year. Analysts estimate the levy can add more than $7 per barrel for VLCCs in some cases, and freight benchmarks have already reacted.
| China Special Port Fees: Industry P&L Impact |
| Story |
Impact |
Business Mechanics |
Bottom-Line Effect |
| Fee schedule starts at 400 yuan per net ton |
Immediate per-call cost for eligible ships from Oct 14, 2025, with scheduled step ups through 2028. |
Applied at the net tonnage scale, collected at Chinese ports, reviewed annually. |
📉 Direct opex uplift per call, 📈 stronger case for emergency surcharges and selective diversions. |
| Scope covers U.S.-owned, operated, built, or flagged vessels |
A wide ownership and control test can touch non U.S. flags if ownership links meet thresholds. |
Ownership, operator, build, or flag connection can trigger the fee, creating counterparty screening needs. |
📉 More KYC time and potential fixture refusals for borderline cases. |
| Exemptions include Chinese-built ships and certain repair calls |
Only first Chinese port on a voyage is charged, and annual charge limits apply per vessel. |
Empty ships to yard for repair can be exempt, collection rules reduce multiple hits on coastal strings. |
📈 Some mitigation for liners with multi port rotations, 📉 residual cost remains material on first call. |
| First high profile case, about $1.7 million fee in Shanghai |
Confirms order of magnitude for large calls and sets expectations for recovery attempts. |
Transparent invoicing triggers contractual review of surcharge rights and bunker adjustment factors. |
📉 Voyage margin compression without rapid pass through, 📈 potential yield lift if surcharges clear. |
| VLCC sensitivity, several dollars per barrel in extreme cases |
Higher effective delivered cost can shift discharge choices and arbitrage windows. |
Levy stacks on freight, insurance, and demurrage, influencing route selection and laycan timing. |
📈 TCE support if diversions lengthen voyages, 📉 negative if demand softens on cost shock. |
| Container lines weigh surcharges versus schedule integrity |
Potential blank sailings, hub changes, and transshipment shifts to neutral nodes. |
Carrier advisories update surcharge tables, terminal windows adjusted to new call patterns. |
📉 Throughput risk at fee heavy gateways, 📈 volume gains at alternative ports and hubs. |
| Banks, insurers, and clubs tighten screening |
More diligence on beneficial ownership and intended Chinese port calls. |
Policy riders address levy exposure, clauses spell out cost allocation and cancellation rights. |
📉 Longer cycle time for fixtures and documentation, 📈 preference for transparent ownership. |
| Freight benchmarks react to policy risk |
Crude routes tighten on diversions and ship scarcity near China, rate volatility increases. |
Tonne miles rise if calls are re sequenced, insurance and operational buffers widen. |
📈 Rate support on lanes with limited substitutes, ↔ mixed for segments with reroute options. |
|
Notes: Summary reflects published measures and market indications. Effects vary by vessel eligibility, contract pass through, and exposure to China linked rotations.
|
The new fee regime lands directly on call economics and then ripples through pricing, routing, and counterparty terms. Operators with flexible rotations and strong contract levers can steady margins while others face a heavier lift. Expect neutral hubs to pick up incremental volume, wider rate dispersion on China-linked corridors, and a premium on transparency and documentation at booking.